
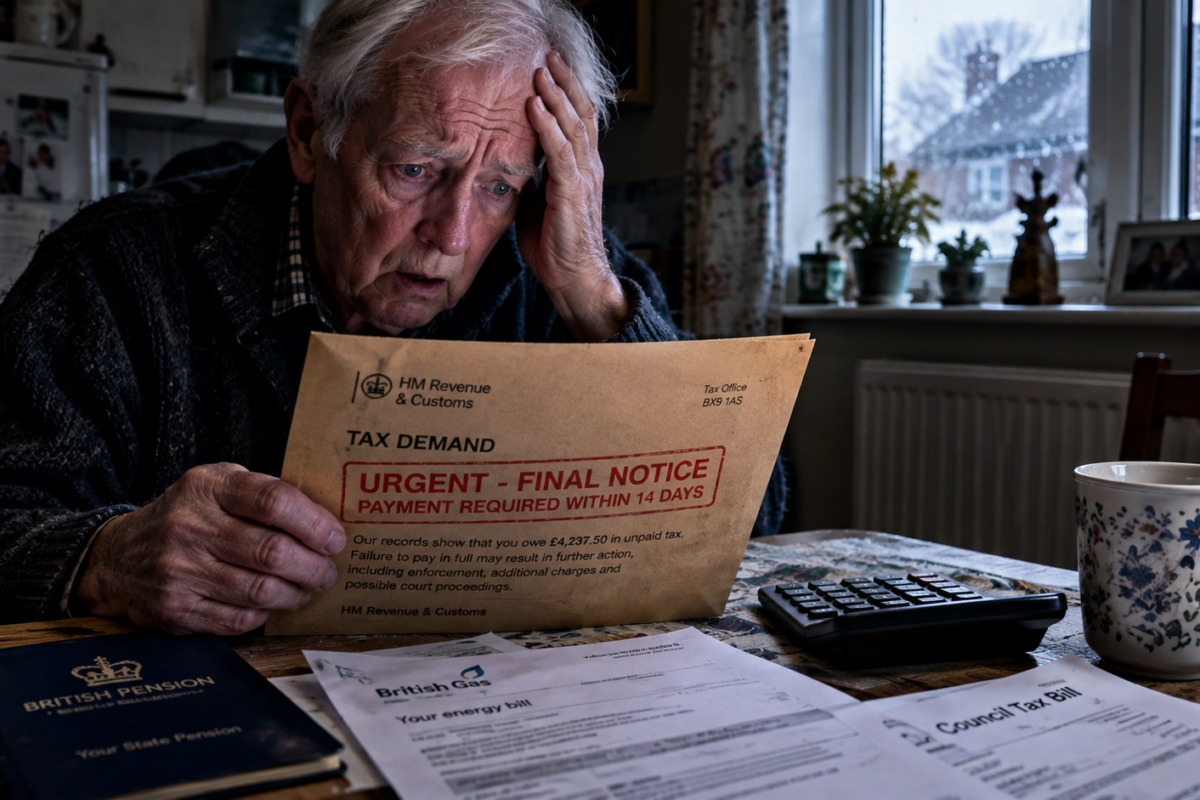
The sudden acceleration of State Pension Tax Trap 2026 alerts has triggered massive nationwide anxiety and urgent discussions across British households, completely altering how millions of retirees plan their everyday living budgets. Retiring after decades of hard work is supposed to provide financial peace of mind backed by the state, but discovering sudden shifts in taxation thresholds can throw long-term domestic budgets into complete disarray. Following the freeze on personal income tax allowances alongside the legal commitment to the pension Triple Lock across the United Kingdom, an unprecedented wave of public concern has emerged surrounding official State Pension Tax Trap 2026 disclosures.
Designed to quietly raise Treasury revenue without raising headline tax rates, this fiscal drag mechanism has created a punitive and unforgiving landscape where unsuspecting older citizens face mandatory income tax deductions on their basic state support. For everyday retirees, assuming that state retirement payments remain entirely tax-free means facing unexpected and financially damaging payment demands under strict State Pension Tax Trap 2026 guidelines. The reality is that HM Revenue and Customs (HMRC), using automated data feeds and tax code alterations, is preparing to pull millions of low-income pensioners into the tax net for the first time in British history.
This straightforward, highly detailed investigative breakdown examines the core facts, detailing the frozen £12,570 personal allowance, the rising Triple Lock payout, the dreaded “simple assessment” tax letters, and the practical steps you must take to protect your retirement fund. Furthermore, financial consumer analysts point out that tracking State Pension Tax Trap 2026 updates represents the most crucial defensive measure for managing household solvency this year. Citizens must adapt quickly to an environment where structural fiscal shifts directly dictate whether an annual pension rise delivers genuine support or triggers an aggressive tax bill. Modern retirement demands absolute vigilance and proactive planning from every pensioner across Britain.
1. The Reality Behind the £12,570 Frozen Allowance and the Triple Lock Collision
The most alarming realization for UK pensioners is that the government’s freeze on income tax thresholds has created an unavoidable financial squeeze, exposing millions to devastating State Pension Tax Trap 2026 announcements.
-
The £12,570 Frozen Cliff Edge: The personal allowance—the amount of income you can receive each year before paying income tax—has been frozen at £12,570 until at least 2028. This political freeze creates immediate planning hurdles and drives the core State Pension Tax Trap 2026 anxiety among retirees surviving on modest incomes.
-
The Triple Lock Acceleration: The State Pension increases each April by the highest of inflation, average wage growth, or 2.5%. Because wage growth and inflation have remained elevated, the annual pension payout is aggressively surging directly toward the frozen allowance.
-
The Inevitable Collision: With the full new State Pension rising toward £12,000 annually, any pensioner with even a microscopic secondary income—such as a £50-a-month workplace pension or modest savings interest—is pushed immediately over the threshold into taxable territory.
-
A Stealth Retirement Tax: Critics and consumer champions have branded the policy a stealth tax on the elderly, pointing out that what the government gives with one hand through the Triple Lock, HMRC reclaims with the other hand under updated State Pension Tax Trap 2026 enforcement mechanisms.
Furthermore, economic advocacy groups emphasize that assuming standard retirement protection covers you from income tax is the primary reason thousands of elderly citizens face sudden financial shocks. Consequently, monitoring official notifications under State Pension Tax Trap 2026 guidelines ensures you know exactly when your total combined income breaches the personal allowance boundary.
2. What Severe Penalties Apply Under State Pension Tax Trap 2026?
Many elderly residents experience severe shock when reviewing their personal mail simply because they do not realize how automated taxation could impact their independence, as detailed in modern State Pension Tax Trap 2026 economic reviews.
-
Shock HMRC “Simple Assessment” Bills: Pensioners who do not have a private pension from which tax can be deducted at source are hit with “Simple Assessment” (P800) letters, demanding lump-sum tax payments of hundreds of pounds by 31 January, reflecting the most terrifying State Pension Tax Trap 2026 data.
-
Frozen Living Budgets: Retirees who budgeted their monthly expenses around their headline pension increase find that a significant portion of their rise is wiped out by 20% basic rate income tax deductions.
-
Depletion of Modest Savings: An inability to pay surprise tax demands forces vulnerable seniors to dip into emergency rainy-day savings originally set aside for boiler repairs or medical emergencies.
-
Aggressive Debt Recovery Actions: If automated tax letters are ignored or lost in the post, HMRC issues escalating statutory penalty surcharges and interest charges, plunging seniors with limited mobility into extreme financial distress under State Pension Tax Trap 2026 parameters.
Understanding these tax collection mechanisms prevents complacency regarding your annual retirement budget. If tax demands arrive unexpectedly in the dead of winter, managing everyday heating and food costs in the United Kingdom becomes an expensive and stressful battle.
3. Administrative Pitfalls and HMRC Coding Errors
Alongside direct fiscal drag, the administrative systems used to track and code pensioner incomes have undergone intense public scrutiny, strongly tied to State Pension Tax Trap 2026 supervision.
-
BR and K Tax Code Chaos: Many pensioners with multiple small private pensions find their tax codes jumbled, resulting in basic rate (BR) or emergency tax being deducted twice from their income, exposing citizens to sudden State Pension Tax Trap 2026 calculation errors.
-
The Lump-Sum Withdrawal Nightmare: Retirees attempting to access modest pension pots under pension freedoms frequently face punitive emergency tax deductions that can take months of complex paperwork to claim back.
-
Failure to Account for Savings Allowance: With interest rates on savings accounts remaining relatively strong, interest from regular bank accounts is automatically reported to HMRC, pushing thousands over the tax boundary without their knowledge.
-
Severe Phone Helpline Delays: Callers trying to reach HMRC to correct an erroneous tax bill face average waiting times exceeding 45 minutes, creating immense frustration for older Britons trying to comply with the rules.
Maintaining vigilance over every tax code notification letter (P2 form) eliminates guesswork when assessing whether your private pension provider is deducting the correct amount.
4. Legal Exemptions: How to Protect Your Pension Income
Even when national tax frameworks enforce severe fiscal freezes, specific legal safeguards and structural options exist under the State Pension Tax Trap 2026 framework.
-
Utilizing Tax-Free ISAs: Shifting cash savings from standard high-street interest accounts into Cash ISAs ensures that all interest generated remains 100% tax-free, preventing savings income from triggering the State Pension Tax Trap 2026 threshold.
-
The Marriage Allowance Transfer: If your spouse has a total income below the £12,570 allowance, they can legally transfer up to £1,260 of their personal allowance to you, cutting your annual tax bill by up to £252.
-
Preserving the 25% Tax-Free Lump Sum: When withdrawing money from private pension pots, ensuring you structure withdrawals using the statutory 25% tax-free lump sum minimizes taxable income in any single fiscal year.
-
Checking Pension Credit Safeguards: Claimants receiving Pension Credit guarantee credit remain protected from certain secondary clawbacks, providing vital breathing room for the lowest-income households.
Specialized advisory groups strongly encourage pensioners to review their complete portfolio of savings and micro-pensions to prevent accidental breaches of the personal allowance limit.
5. Simple Checklist: Steps to Protect Your Retirement Income
To ensure your retirement finances remain entirely legal and unexpected tax demands are avoided, follow this practical checklist inspired by State Pension Tax Trap 2026 defense strategies:
-
Calculate Total Annual Income: Add your full State Pension amount to any private, workplace, or annuity income to verify whether your gross annual total exceeds £12,570.
-
Audit Your Bank Interest: Check how much interest your non-ISA savings accounts generate each year; for basic-rate taxpayers, interest exceeding £1,000 per year is subject to tax.
-
Inspect Your PAYE Tax Codes: Carefully review any coding notices sent by HMRC for private pensions, ensuring your personal allowance has been applied correctly to the primary payment.
-
Open a Cash ISA Immediately: Protect your rainy-day reserves from automated HMRC reporting by utilizing your annual £20,000 tax-free ISA allowance.
-
Set Aside Tax Contingency Funds: If your total income is projected to sit between £13,000 and £15,000, set aside approximately £100 to £300 to settle potential Simple Assessment bills without stress.
Proactive pension audits completed today eliminate administrative panic and protect your hard-earned retirement income throughout the year.
6. Frequently Asked Questions (FAQs)
Why is the State Pension becoming taxable under the State Pension Tax Trap 2026 rules?
The personal tax allowance is legally frozen at £12,570 until 2028, while the State Pension increases every year due to the Triple Lock. As the pension approaches and eventually overtakes £12,570, any additional income pushes retirees into the tax system.
How will HMRC collect tax from state pensioners?
The State Pension itself is paid without tax deducted. If you have a private pension, HMRC will alter that pension’s tax code to collect the tax. If you only have the State Pension and a small amount of savings or part-time earnings, HMRC will send a “Simple Assessment” bill demanding direct payment.
Can I be fined if I fail to pay a Simple Assessment tax bill?
Yes. If HMRC issues a Simple Assessment demand and the bill is not settled or challenged by the specified deadline (usually 31 January), statutory interest and late-payment penalties apply automatically.
Where can I check official UK retirement and tax advice?
You can review authoritative government tax tables, check your State Pension forecast, and monitor personal allowances directly through the official GOV.UK portal or by consulting independent guidance from Pension Wise.
Conclusion: Don’t Let Stealth Taxes Erode Your Retirement
Keeping up with ongoing State Pension Tax Trap 2026 discussions is essential for protecting your financial freedom and maintaining a stress-free retirement for your household. With tax thresholds frozen in place and pension uplifts narrowing the gap every single month, taking a few minutes to audit your annual income, transfer cash to tax-free ISAs, and inspect your tax codes can completely safeguard your monthly cash flow from unexpected HMRC bills.
Make sure your financial arrangements are thoroughly audited before the end of the current tax year. Navigating these complex taxation realities successfully is the ultimate key to achieving long-term peace of mind in your later years. Understanding the extreme State Pension Tax Trap 2026 implications is critical for anyone planning or currently enjoying retirement across the UK. For continuous updates, breaking financial news, and essential pensioner advice, make sure to bookmark and regularly visit Go Daily Buzz.
Join the conversation