
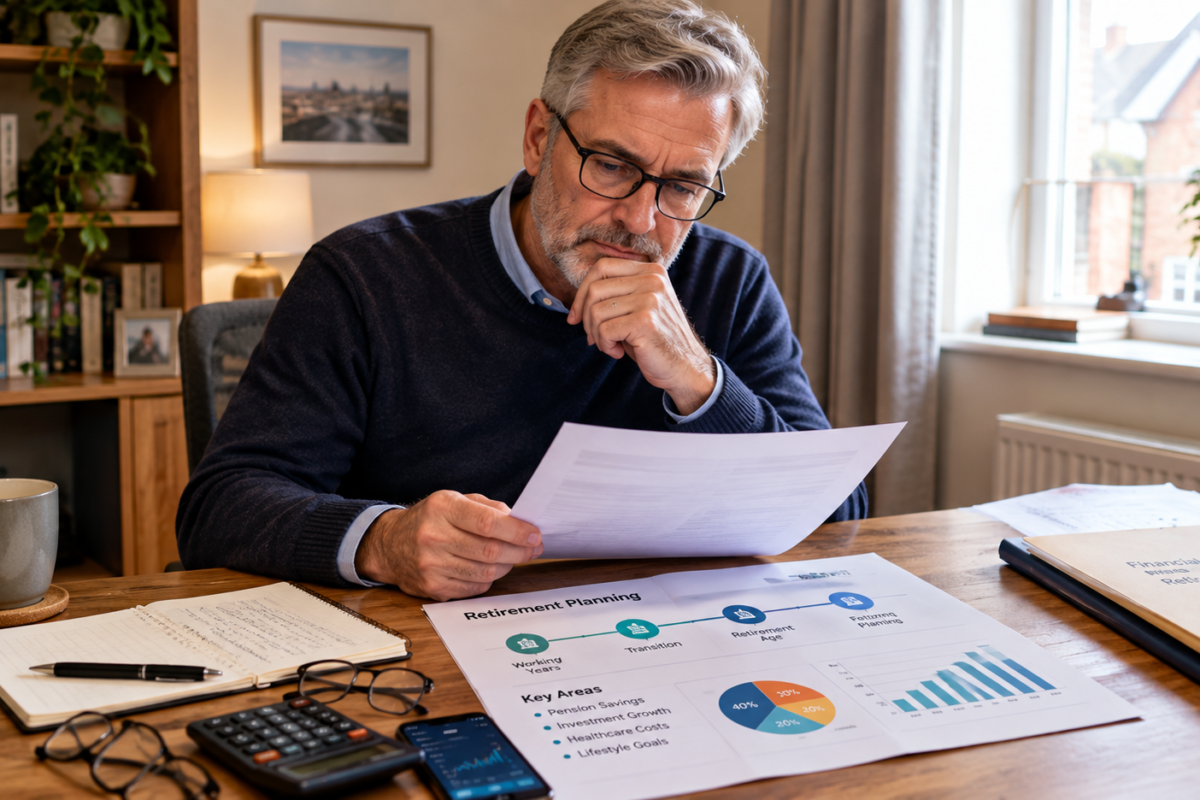
For millions of workers, career employees, self-employed individuals, business owners, and families planning for their future retirement across the United Kingdom, keeping track of government policy shifts has become an increasingly stressful and demanding financial responsibility. Following successive treasury reviews, demographic shifts, and mounting fiscal pressures on public finances, the ongoing debate surrounding uk state pension age hikes has officially taken center stage in national news, parliamentary discussions, and public discourse.
Designed to ensure the long-term solvency and financial sustainability of the state pension system amidst an aging British population, these structural policy adjustments are reshaping the traditional retirement landscape. For younger generations and mid-career workers alike, the target age at which they can claim their state pension is moving further away, creating unprecedented anxiety about future financial stability and career longevity. However, these sweeping policy revisions introduced under the uk state pension age hikes raise critical, complex questions for British households regarding financial planning, career management, personal savings, healthcare readiness, and intergenerational equity.
This comprehensive, highly detailed, and data-driven investigative guide breaks down the core elements of the uk state pension age hikes, examining the exact timeline projections, the official government rationale, the economic implications across various industries, and actionable financial strategies workers can deploy right now to prepare successfully for the uk state pension age hikes.
1. Comprehensive Breakdown of the Current State Pension Timeline
Understanding the exact trajectory of retirement age increases requires looking closely at legislative roadmaps established by the Department for Work and Pensions (DWP) and His Majesty’s Treasury. The transition toward higher retirement thresholds is happening in phased legislative steps that impact different age cohorts uniquely across the nation.
-
Current State Pension Age Baseline and Historical Context: For both men and women across the United Kingdom, the state pension age currently sits at 66. This baseline was reached following a multi-year equalization and raising process mandated by previous parliamentary acts designed to close the historical gap between male and female retirement eligibility, establishing a unified entry point.
-
The Transitional Phase to Age 67: Under existing legislative schedules tied to the uk state pension age hikes, the state pension age is legislated to rise gradually to 67 between 2026 and 2028. This affects anyone born between specific qualifying years, requiring millions of workers to adjust their working horizons, career plans, and personal savings goals by an additional 12 months of mandatory employment.
-
Projected Accelerated Rise to Age 68: Government reviews have heavily signaled that the subsequent scheduled rise—moving the state pension age from 67 to 68—could be significantly accelerated. Originally planned for the mid-2040s, policymakers are actively reviewing updated Office for National Statistics (ONS) demographic data and life expectancy trends to determine if this shift needs to happen much earlier to manage public sector liabilities under the uk state pension age hikes.
-
Equal Treatment Across Demographics and Birth Milestones: Unlike historical frameworks that maintained disparate retirement ages for men and women, modern legislative adjustments ensure a standardized retirement threshold regardless of gender, governed purely by precise date of birth milestones set by parliamentary legislation.
-
Checking Personal Qualifying Dates via Digital Portals: Because individual state pension ages depend entirely on exact birth dates and complex National Insurance contribution histories, workers are strongly encouraged to utilize official government digital checking portals to identify their exact projected retirement milestone under the uk state pension age hikes.
-
Legislative Review Triggers and Independent Assessments: The Department for Work and Pensions is legally required to conduct regular independent reviews of life expectancy data, macroeconomic forecasts, and fiscal sustainability metrics, meaning that further adjustments, delays, or accelerations to the uk state pension age hikes remain a distinct possibility for future parliamentary sessions.
Additionally, public sector analysts point out that the transition period has severe implications for individuals operating in regions with lower average life expectancies, where the effective duration of retirement is disproportionately compressed compared to more affluent metropolitan areas. This geographic disparity has fueled ongoing parliamentary debates regarding whether a blanket retirement age is equitable across diverse socio-economic backgrounds in the United Kingdom. Furthermore, trade unions and labor representatives have consistently argued that raising the state pension age disproportionately penalizes manual workers who began their careers straight out of secondary school in their teens.
These individuals have often accumulated over four decades of arduous physical labor by the time they reach their mid-sixties, making the prospect of extending their working lives an immense physical and mental strain. Government commissions continue to evaluate whether occupational exemptions or flexible drawdown models could eventually be introduced to mitigate these glaring disparities.
2. The Official Rationale: Demographics, Longevity, and Treasury Pressures
The profound push behind the continuous implementation of uk state pension age hikes stems from overwhelming demographic realities, soaring public expenditure, and the sheer fiscal cost of funding a rapidly aging British society in a competitive global economy.
-
Surging Life Expectancy Trends and Public Health Gains: Over the past several decades, average life expectancy across the United Kingdom has risen significantly due to advancements in medical science, healthcare treatments, and living standards. While this represents a positive public health milestone, it means retirees are drawing state pension funds for a much longer duration than originally anticipated when the modern welfare system was first designed.
-
The Worker-to-Retiree Ratio Imbalance: The ratio of tax-paying workers actively contributing to the national insurance pool compared to retired citizens claiming state benefits has narrowed dramatically, putting immense structural strain on public finances and threatening the long-term stability of government welfare budgets.
-
Fiscal Sustainability of the Treasury and National Debt Management: Government officials maintain that without proactive uk state pension age hikes, the sheer cost of funding the state pension triple lock and annual disbursements would become an unsustainable fiscal burden on future generations of taxpayers, risking national credit ratings and sovereign borrowing costs.
-
Balancing Competing Public Sector Budgets: National insurance contributions and general taxation revenues must be balanced carefully across competing public infrastructure demands, including National Health Service (NHS) waiting lists, educational facilities, social care networks, and national defense commitments.
-
International Comparative Benchmarks Across Western Economies: The UK’s legislative approach mirrors broader international trends across Western economies, where governments are raising retirement ages in response to global demographic shifts, declining birth rates, and rising sovereign debt deficits.
-
Mitigating Generational Inequality and Welfare Solvency: Policymakers argue that adjusting retirement timelines gradually helps protect the long-term solvency of the welfare state, ensuring that state pension support remains viable, funded, and operational for decades to come without collapsing under generational imbalances.
Moreover, economists emphasize that sovereign pension liabilities interact directly with broader macroeconomic indicators, including gilt yields, national productivity growth, and public sector borrowing requirements. When global financial markets experience volatility, the cost of servicing government debt increases, leaving the Treasury with very few policy instruments outside of structural reforms and retirement age recalibrations to stabilize national expenditure profiles over the medium term.
Furthermore, the debate surrounding national insurance receipts and general treasury taxation mechanisms highlights a fundamental structural dilemma: as automation and artificial intelligence reshape the modern labor market, the total pool of traditional wage-based contributions may contract, placing even greater fiscal reliance on government policy levers like retirement age adjustments to balance national balance sheets.
3. Financial Implications for Mid-Career Workers and Future Retirees
The practical reality of facing extended working years due to uk state pension age hikes introduces substantial financial, physical, and professional hurdles for everyday citizens attempting to plan their futures securely.
-
Extended Working Lifespans and Career Fatigue: Workers who planned their personal finances around retiring comfortably at age 65 or 66 now find themselves forced to maintain full-time employment for additional years, altering long-term career planning, personal wellbeing, mental health, and family time.
-
Physical Demands on Manual Laborers and Trade Workers: Trade workers, manual laborers, construction staff, and individuals in physically demanding occupations face severe challenges regarding health, chronic pain, injury risks, and physical endurance when forced to work longer under the uk state pension age hikes.
-
The Private Savings Gap Challenge: Pushing back the state pension age creates an immediate financial “gap year” for individuals who intended to stop working earlier, requiring significantly larger private pension pots to bridge the unexpected income shortfall before state support kicks in.
-
Impact on Workplace Retirement Planning and Corporate HR: Employers and corporate human resources departments are being forced to rapidly adapt to an older workforce, reviewing flexible working arrangements, phased retirement models, health support structures, and workplace ergonomics.
-
State Pension Triple Lock Debates and Income Uncertainty: While workers wait longer to qualify, ongoing political debates surrounding the future, funding mechanisms, and potential reform of the state pension triple lock add further uncertainty to long-term retirement income projections.
-
Compounding Household Financial Stress: For households already squeezed by the rising cost of living, soaring housing costs, and persistent inflation, adjusting personal retirement savings strategies to account for uk state pension age hikes requires difficult budgetary sacrifices.
Financial advisors note that the psychological toll of working past traditional retirement thresholds is frequently underestimated. Mid-career professionals face mounting burnout, while older workers transitioning into consultancy or part-time roles often encounter age-related friction in hiring markets, making proactive financial cushioning an absolute necessity before reaching their late fifties. The ripple effects of these policy shifts also extend into familial dynamics, where older workers frequently find themselves caught in the ‘sandwich generation’—simultaneously supporting aging parents with specialized care needs and providing financial assistance to adult children struggling to secure affordable housing.
Balancing these multi-generational financial obligations while navigating delayed state pension eligibility creates a complex web of budgetary pressures for modern British families. In addition to individual financial planning and corporate policy adjustments, policymakers are continuously examining how regional economic inequalities across the United Kingdom influence retirement readiness.
Workers residing in economically depressed post-industrial or rural regions often experience significantly lower average household savings and fewer private pension assets compared to those located in major financial hubs like London and the Southeast. Consequently, structural policy decisions regarding national retirement milestones must carefully weigh aggregate macroeconomic targets against localized socio-economic realities to ensure that vulnerable communities are not left behind in the government’s broader fiscal strategy.
4. How to Bridge the Retirement Gap: Actionable Financial Strategies
Facing the reality of the uk state pension age hikes means individuals must take proactive control of their personal finances well before their designated retirement milestone to secure financial independence and peace of mind.
-
Maximize Workplace and Private Pension Contributions: Relying solely on the state pension is no longer a viable retirement strategy. Accelerating contributions into workplace defined-contribution schemes or private personal pensions is essential to build an independent financial cushion.
-
Utilize Tax-Efficient Savings Vehicles and ISAs: Fully leveraging Individual Savings Accounts (ISAs) and pension tax reliefs allows savers to compound their investments free from heavy capital gains and income tax liabilities over the long term.
-
Conduct Regular Comprehensive Pension Audits: Consolidate old workplace pensions from past employers into a single, manageable digital portfolio to minimize administrative management fees and maximize overall investment growth potential.
-
Explore Phased Retirement and Flexible Work Models: Rather than stopping work abruptly at a fixed age, many modern workers transition into part-time employment, consultancy, or flexible freelance roles to ease into retirement while maintaining steady income streams.
-
Review and Eliminate Personal Debt Obligations: Entering your late 50s and 60s free of major consumer debt, credit card balances, and mortgages significantly reduces the monthly income required to sustain your lifestyle during retirement.
-
Consult Accredited Professional Financial Advisors: Navigating complex pension regulations, tax bands, lifetime allowances, and investment portfolios benefits greatly from personalized guidance provided by accredited financial advisors.
Beyond standard pension contributions, modern wealth management strategies increasingly emphasize the diversification of income streams through property assets, dividend-paying equities, and entrepreneurial side ventures. Building a robust emergency fund ensures that unexpected economic shocks or early involuntary retirement do not derail a household’s long-term financial planning objectives. Financial literacy campaigns launched by independent consumer advocacy groups stress the importance of starting retirement planning as early as possible in one’s career.
Utilizing compound interest calculators, understanding employer match schemes, and reviewing projected annuity rates versus drawdown flexibilities can dramatically alter an individual’s financial preparedness decades before their actual retirement date arrives. Furthermore, public sector consultations highlight that as digital banking and automated pension management platforms become the primary tools for tracking retirement assets, digital exclusion among elderly or lower-income demographics remains a pressing policy concern that requires targeted administrative support and accessible offline channels.
Ultimately, proactive consumer awareness and early financial engagement represent the most effective defense against the compounding pressures of shifting retirement horizons in the modern British economy.
5. Employer Responsibilities and Workplace Adaptations
As the workforce ages in response to government policy, British employers face new operational demands and ethical responsibilities to support older employees effectively throughout their extended careers.
-
Adapting Health and Safety Policies for Older Staff: Companies employing manual labor or active staff must reevaluate workplace ergonomics, health assessments, and injury prevention programs specifically tailored for older workers.
-
Implementing Flexible Working and Remote Options: Offering remote work arrangements, job-sharing, and reduced hours allows experienced older staff to remain productive without facing physical or mental burnout.
-
Investing in Continuous Digital Retraining: Providing ongoing digital and professional skills training ensures older workers remain valuable assets in an increasingly automated, technology-driven modern economy.
-
Establishing Formal Phased Retirement Pathways: Forward-thinking organizations are establishing formal phased retirement schemes that allow employees to scale back working hours gradually over a multi-year transition period.
-
Expanding Mental Health and Wellbeing Support: Recognizing the unique psychological pressures of extended careers, employers are expanding mental health resources tailored specifically to mid-career and older demographics.
-
Managing Intergenerational Teams Effectively: Building collaborative environments where older, experienced workers mentor younger colleagues fosters institutional knowledge retention across British industries.
Progressive corporate governance models are beginning to recognize that retaining older, experienced personnel through ergonomic workplace adaptations and phased retirement not only boosts company morale but also preserves vital institutional knowledge that would otherwise be lost during rapid staff turnovers. Finally, corporate leaders are discovering that fostering an age-inclusive workplace culture yields measurable productivity benefits. uk state pension age hikes By dismantling age-related biases in recruitment and training, companies can harness the invaluable problem-solving skills and emotional intelligence of seasoned employees, creating a more resilient and adaptable workforce capable of navigating future economic shifts.
6. Frequently Asked Questions (FAQs)
When will the state pension age officially rise to 67?
Under current legislation driven by the uk state pension age hikes, the state pension age is scheduled to increase from 66 to 67 progressively between 2026 and 2028.
Is the state pension age guaranteed to reach 68?
While a rise to age 68 is currently planned for future decades, government reviews continue to assess demographic data, meaning the timeline for uk state pension age hikes remains subject to parliamentary adjustment.
Can I choose to claim my state pension earlier than my official age?
No. Unlike private pensions which often allow access from age 55 or 57, the state pension cannot be claimed under any circumstances before reaching your statutory state pension age.
How can I check my exact state pension age?
You can verify your precise retirement age, qualifying National Insurance years, and projected payout by logging into the official “Check your State Pension” portal on GOV.UK.
Do years spent caregiving or unemployed count toward my pension?
Yes. Certain periods—such as raising children, claiming registered carer benefits, or receiving specific unemployment credits—can count as qualifying years toward your final state pension entitlement.
“For deeper legislative insights into how parliamentary committees assess demographic pressures and workforce readiness, you can review the official findings detailed in the UK Parliament Transition to State Pension Report…”
Conclusion: Navigating the Future of Retirement Amidst Policy Shifts
The ongoing reality of uk state pension age hikes highlights the profound demographic and financial transformations taking place across the United Kingdom. While citizens cannot alter government-backed legislative timelines or macro-level fiscal policies, understanding the exact retirement roadmap empowers workers to take proactive control of their personal savings, career planning, and long-term financial security.
As economic forecasts, labor market trends, and government guidelines continue to evolve throughout the year, staying informed on breaking national financial news is essential for modern consumers. The sweeping impact of the uk state pension age hikes continues to unfold. Experts agree that the uk state pension age hikes will change retirement planning forever. Workers must prepare for the uk state pension age hikes. Staying vigilant and well-informed is paramount for securing long-term financial stability. Every single citizen must plan ahead. For continuous updates, in-depth financial breakdowns, and essential guidance regarding the uk state pension age hikes, make sure to bookmark and regularly visit Go Daily Buzz.
Join the conversation