
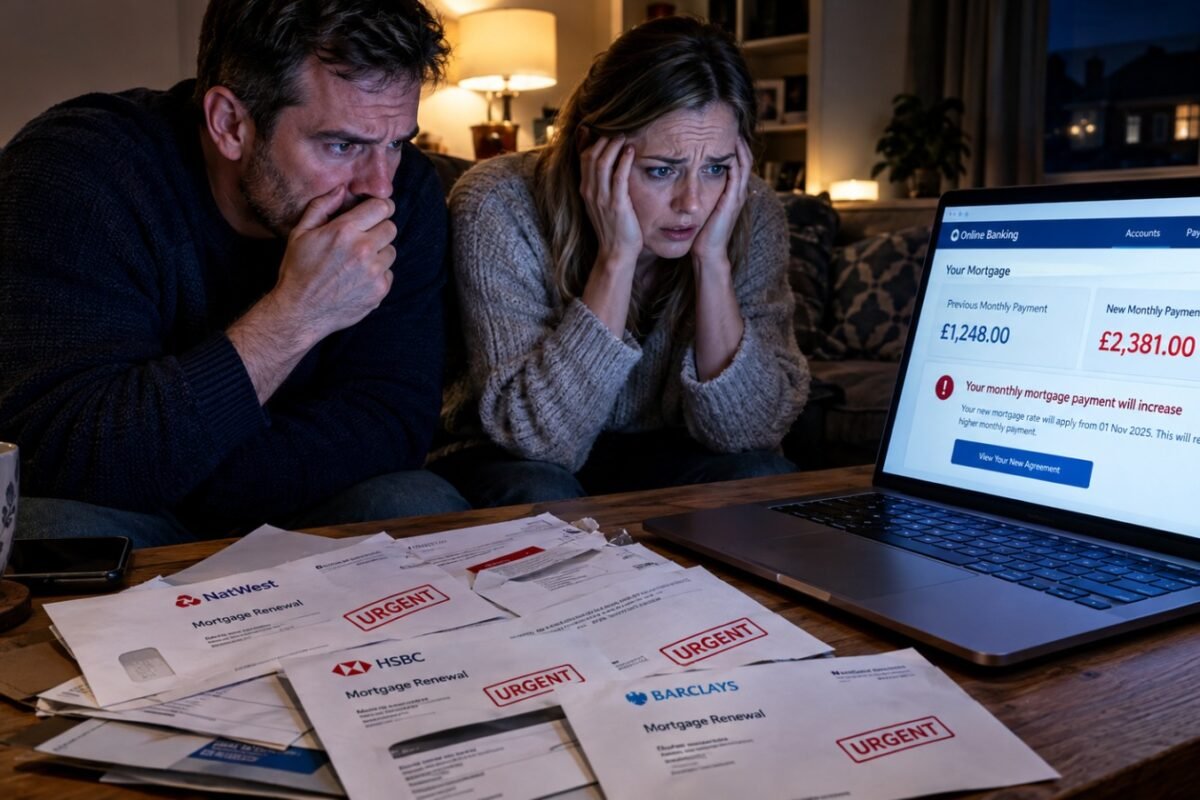
uk mortgage interest rates shock 2026 warnings have sparked widespread anxiety, completely transforming how British homeowners, first-time buyers, and property investors view borrowing costs across the United Kingdom. Managing personal finances has grown increasingly difficult, but absorbing sudden monthly loan surges is proving to be a breaking point for millions. Following recent announcements regarding Bank of England base rate adjustments, an explosive wave of panic has emerged surrounding official uk mortgage interest rates shock 2026 letters arriving on doormats nationwide.
Designed to stabilize macroeconomic lending standards under the guise of inflation control, aggressive rate resets have created a financial trap where unsuspecting borrowers face steep, unexpected debt. For everyday homeowners, assuming that historic low rates will return or expecting seamless transitions between fixed deals means facing sudden financial strain under uk mortgage interest rates shock 2026 guidelines.
This straightforward investigative breakdown examines the core uk mortgage interest rates shock 2026 facts, detailing hidden tracker rate escalations, administrative refinancing delays, and practical steps to secure competitive deals early. Furthermore, economic analysts point out that tracking uk mortgage interest rates shock 2026 updates represents the most crucial defensive measure for domestic budget management this year. Citizens must adapt quickly to an environment where lending rate shifts directly threaten household savings. Modern living standards demand absolute vigilance from every property owner across Britain.
1. The Reality Behind the UK Mortgage Interest Rates Shock 2026
The most alarming realization for UK borrowers is that expiring fixed-rate deals are rolling onto drastically higher Standard Variable Rates (SVR), as highlighted by recurring uk mortgage interest rates shock 2026 disclosures across major lenders.
-
The Fixed-Rate Cliff-Edge: Millions of fixed deals secured during past low-interest periods are terminating, driving the core uk mortgage interest rates shock 2026 surge as monthly repayments jump significantly.
-
The Tracker Rate Trap: Homeowners tied to variable or tracker mortgages face immediate monthly payment increases every time central bank rates fluctuate, a hidden mechanism driving many uk mortgage interest rates shock 2026 complaints.
-
Lender Affordability Stress Tests: Refinancing current balances requires navigating stricter lending criteria, creating an overlapping qualification barrier under uk mortgage interest rates shock 2026 parameters.
-
Regional Property Valuation Dips: Areas experiencing sluggish housing market growth face equity shortfalls, sparking fierce debates regarding uk mortgage interest rates shock 2026 borrowing limits.
-
Corporate Lender Profit Margins: Financial transparency groups continue to expose high standard variable rates charged by major high-street banks, fueling public outrage over why uk mortgage interest rates shock 2026 repayments keep climbing despite stabilizing inflation.
Furthermore, consumer advocacy groups emphasize that assuming current lenders will automatically offer the best retention deals is the primary reason millions overpay each year. Mortgage billing structures frequently contain legacy product fees that remain unexamined. Consequently, monitoring financial institution announcements under uk mortgage interest rates shock 2026 guidelines ensures households stay informed about sudden market shifts. In addition to reviewing official mortgage statements, residents should inspect alternative lender rates. Financial advisors strongly recommend auditing refinancing timelines independently. Understanding these structural risks protects domestic finances from unauthorized lender overreach. Borrowers emphasize that early product locking is the ultimate defense against inflated instalments.
2. What Financial Pressures Are Associated With Loan Surges?
Many residents experience severe shock when opening their new repayment schedules simply because they do not realize how cumulative interest adjustments impact monthly budgets, as detailed in modern uk mortgage interest rates shock 2026 economic reviews.
-
Household Budget Squeezes: Surging monthly loan repayments eat directly into disposable income, leaving families with fewer resources for groceries and energy essentials as warned by uk mortgage interest rates shock 2026 data.
-
Increased Arrears and Possession Risks: Persistent payment failures due to unaffordable rate leaps trigger aggressive lender debt recovery actions and legal proceedings under uk mortgage interest rates shock 2026 protocols.
-
Disproportionate Impact on Young Families: Recent first-time buyers juggling high property prices struggle immensely to absorb recurring monthly increases, prompting emergency financial planning shifts within recent uk mortgage interest rates shock 2026 briefs.
-
Rental Market Spillover Effects: Landlords facing elevated buy-to-let mortgage costs frequently pass financial burdens directly onto tenants through higher monthly rents, magnifying the economic shock of uk mortgage interest rates shock 2026 across housing sectors.
-
Stagnant Property Mobility: High borrowing costs trap homeowners in their current properties, preventing essential relocations and intensifying frustration over uk mortgage interest rates shock 2026 lending policies.
Understanding these financial consequences prevents complacency regarding domestic expense tracking. If loan repayments escalate unchecked, managing household cash flow becomes nearly impossible. Economic associations have widely discussed how exposing these pressures redefines domestic financial planning under uk mortgage interest rates shock 2026 parameters. Knowing these budgetary risks ensures households prioritize proactive refinancing checks. Furthermore, understanding economic impacts avoids unexpected debt accumulation during billing cycles.
3. Administrative Delays and Valuation Discrepancies
Alongside direct percentage increases, lending application processing accuracy has undergone intense public scrutiny across select UK regions under updated investigations tied to uk mortgage interest rates shock 2026 supervision.
-
Six-Month Offer Windows: Securing a remortgage offer up to six months before a current deal expires is standard practice, but administrative backlogs expose borrowers to sudden uk mortgage interest rates shock 2026 policy shifts.
-
Incorrect Property Valuations: Many homes are undervalued during automated surveying processes, placing borrowers into higher loan-to-value (LTV) brackets highlighted in uk mortgage interest rates shock 2026 reports.
-
Failure to Account for Energy Efficiency: Eco-friendly home modifications that improve property marketability are frequently ignored by mortgage underwriters, leading to missed green-rate discounts.
-
Delayed Product Transfer Processing: Internal bank delays routinely experience administrative bottlenecks, causing temporary jumps onto expensive SVR rates under uk mortgage interest rates shock 2026 collection schedules.
Citizens must review their regional property valuation records and lender communication indexes to ensure absolute awareness of uk mortgage interest rates shock 2026 disclosures and statutory lending standards. Maintaining vigilance over financial paperwork eliminates guesswork when assessing repayment accuracy.
4. Special Exemptions and Mortgage Support Schemes
Even when financial markets face widespread borrowing challenges, specific domestic relief measures and legal protocols protect vulnerable borrowers under uk mortgage interest rates shock 2026 guidelines.
-
Support for Mortgage Interest (SMI): Eligible homeowners receiving specific qualifying state benefits can apply for government loans to help pay the interest on their mortgages.
-
Mortgage Charter Protections: Major UK lenders signed an agreement allowing borrowers to temporarily switch to interest-only payments or extend their loan terms without impacting their credit scores, a relief featured during uk mortgage interest rates shock 2026 rollouts.
-
Payment Holiday Regulations: While traditional payment holidays are no longer issued freely, lenders are mandated to offer tailored forbearance options for customers facing acute financial hardship.
-
Product Transfer Flexibility: Switching to a new fixed deal with an existing lender without undergoing fresh affordability stress tests remains a key option under uk mortgage interest rates shock 2026 rules.
Specialized consumer bodies have praised the practical utility of relief schemes under uk mortgage interest rates shock 2026 supervision, ensuring eligible families can access vital financial support.
5. Simple Checklist: How to Check and Secure Your Mortgage Rate
To ensure your family remains financially secure and high interest charges are avoided, follow this practical household checklist inspired by uk mortgage interest rates shock 2026 defense strategies:
-
Note Your Expiry Date: Check your current mortgage documentation today to identify the exact month your fixed-rate deal ends.
-
Lock in a Rate Early: Apply for a new remortgage deal up to six months in advance to protect against sudden market rate increases.
-
Review Product Transfer Options: Compare your current lender’s retention rates against whole-market broker offers to find the cheapest monthly repayment.
-
Improve Loan-to-Value (LTV): Pay down a lump sum before refinancing if possible, dropping your LTV into a lower bracket for better interest rates.
-
Contact Lender Support Early: If you anticipate payment difficulties following uk mortgage interest rates shock 2026 notices, reach out to your provider immediately to arrange a manageable payment restructuring plan.
Proactive domestic habits established today prevent long-term debt accumulation and ensure absolute fairness in home loan management.
6. Frequently Asked Questions (FAQs)
How far in advance can I lock in a new mortgage rate in the UK?
Most UK lenders allow you to secure a new remortgage deal up to six months before your current fixed-rate period expires, protecting you from sudden market spikes under uk mortgage interest rates shock 2026 frameworks.
What happens when my fixed-rate mortgage ends?
If you do not choose a new deal, your loan automatically rolls onto your lender’s Standard Variable Rate (SVR), which is typically much higher and increases your monthly payments.
Can I switch to a different lender if I have bad credit?
Yes, specialist remortgage brokers can help find lenders who cater to adverse credit histories, though interest rates may be higher compared to prime market products.
Where can I check official borrowing guidance and lender comparisons?
You can review authoritative financial conduct frameworks, interest rate trackers, and consumer borrowing advice directly by visiting the official Financial Conduct Authority (FCA) Portal.
Conclusion: Don’t Let Interest Rate Shocks Drain Your Wallet
Staying ahead of ongoing uk mortgage interest rates shock 2026 discussions is essential for protecting your household finances and avoiding silent overpayments. With lenders adjusting product lines and fixed deals expiring, taking a few minutes to evaluate your mortgage options and lock in rates early can safeguard your family’s economic well-being.
Make sure your home loan arrangements are secure before your current deal lapses. Navigating uk mortgage interest rates shock 2026 realities successfully is the ultimate key to maintaining a balanced household budget. For continuous updates, breaking financial news, and essential consumer advice regarding uk mortgage interest rates shock 2026 alerts, make sure to bookmark and regularly visit Go Daily Buzz.
Join the conversation