
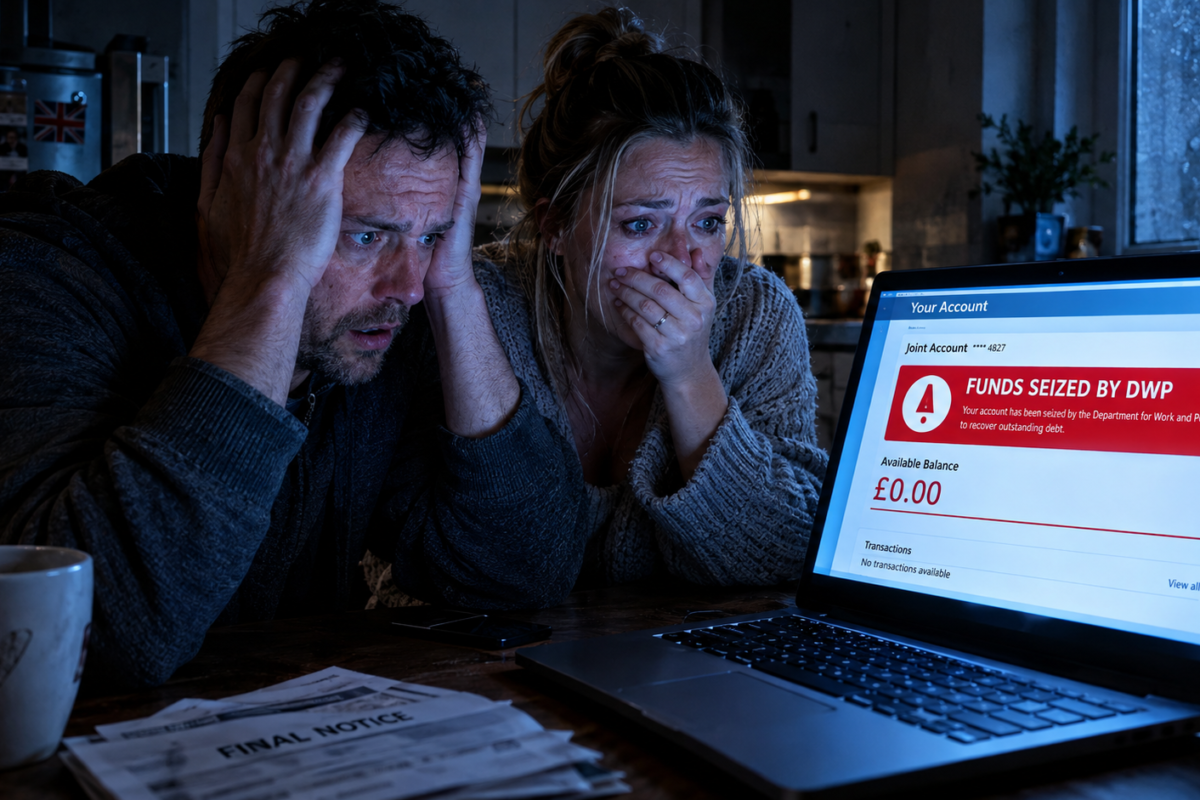
The sudden wave of DWP Joint Account Crackdown 2026 alerts has triggered massive nationwide anxiety and urgent discussions across British households, completely altering how benefit claimants and their partners manage their personal finances. Storing your hard-earned money in a shared high-street bank is supposed to offer basic financial security, but discovering sudden shifts in welfare enforcement can throw long-term personal stability into complete disarray. DWP Joint Account Crackdown 2026 Following an explosive government announcement detailing the biggest crackdown on welfare debt in a generation under the new Public Authorities (Fraud, Error and Recovery) Act, an unprecedented wave of public concern has emerged surrounding official DWP Joint Account Crackdown 2026 disclosures.
Designed to aggressively claw back billions in overpaid welfare under shifting economic pressures, these highly rigid debt recovery rules have created a punitive and unforgiving landscape where unsuspecting citizens face extreme financial penalties and sudden bank withdrawals. DWP Joint Account Crackdown 2026 For everyday welfare claimants—especially those who are no longer claiming benefits but still hold historical debt—assuming that historical court protections will remain static means facing unexpected and financially ruinous direct deductions under strict DWP Joint Account Crackdown 2026 guidelines. The reality is that the welfare state is increasingly relying on absolute legal authority to bypass the courts entirely, leaving the most vulnerable members of society fighting automated government debt collectors.
This straightforward, highly detailed investigative breakdown examines the core facts, detailing the terrifying reality of Direct Deduction Orders (DDOs), the severe threat to your partner’s savings, the potential loss of your driving licence, and the practical steps you must take to secure your financial itinerary. DWP Joint Account Crackdown 2026 Furthermore, financial consumer analysts point out that tracking
DWP Joint Account Crackdown 2026 updates represents the most crucial defensive measure for managing long-term domestic stability this year. Citizens must adapt quickly to an environment where structural welfare shifts directly dictate whether a simple administrative error ends in a compassionate repayment plan or a sudden emptying of your bank account. Modern welfare reliance demands absolute vigilance and proactive planning from every single claimant across Britain.
1. The Reality Behind the New Legal Powers and Direct Deductions
The most alarming realization for UK claimants is that official privacy and legal thresholds are shifting aggressively downwards to crack down on overpayments, exposing millions to devastating DWP Joint Account Crackdown 2026 realities.
-
The End of Court Orders: The new Public Authorities (Fraud, Error and Recovery) Act explicitly states that officials can now go directly to a person’s bank to claw back cash owed via a Direct Deduction Order (DDO), without needing a judge or a court order. This zero-tolerance transition creates immediate planning hurdles and drives the core DWP Joint Account Crackdown 2026 anxiety among those trying to manage historical benefit debts.
-
Closing the PAYE Loophole: Previously, if a claimant stopped receiving benefits and was not in the PAYE tax system, it was extremely difficult for the government to recover old debts. The new laws specifically target these individuals, ensuring that stepping off the welfare system does not erase historical financial liabilities.
-
The Massive £14.6 Billion Savings Target: The government is aiming to ruthlessly make savings of £14.6 billion over the next five years specifically from fraud, error, and debt activity. To hit this massive quota, internal debt collection teams will be under immense pressure to execute the DWP Joint Account Crackdown 2026 sweeps quickly and efficiently.
-
Automated Affordability Checks: While the government claims that “affordability and vulnerability checks” will be carried out before deductions are made to ensure people can still buy food, critics argue that automated digital checks cannot accurately assess the nuanced daily struggles of a low-income household.
2. Why Joint Accounts Are Being Aggressively Targeted
Many hard-working residents experience severe shock when reviewing their government mail simply because they do not realize how strict digital enforcement could impact their innocent family members, as detailed in modern DWP Joint Account Crackdown 2026 economic reviews.
-
The 50/50 Ownership Assumption: In a terrifying escalation, the government’s official Code of Practice states that they will presume joint account holders each have an “equal share of the funds” (50%). This means they can legally seize up to half of the total balance to pay off a debt that belongs to only one person.
-
The Threat to Non-Claimants: The most controversial aspect of the DWP Joint Account Crackdown 2026 policy is that innocent partners who have never claimed benefits themselves could wake up to find their wages completely drained just because their name is on a shared banking mandate.
-
The Burden of Proof is on You: If an innocent partner believes their money should not be seized, they are forced to frantically provide extensive legal and financial evidence to the government to prove that the funds do not belong to the debtor—a process that can take weeks while the money remains frozen.
-
Bouncing Bills and Rent Arrears: Claimants fear that if their joint accounts are raided without prior negotiation, Direct Debits for rent, mortgages, and energy bills will suddenly bounce, instantly plunging families who already live below the poverty line into severe debt traps.
3. The Ultimate Threat: Stripping Your Driving Licence
Alongside direct banking policy adjustments, extreme personal enforcement methods have undergone intense public scrutiny across global administrative channels, strongly tied to DWP Joint Account Crackdown 2026 supervision.
-
The £1,000 Threshold: For individuals who deliberately and persistently evade repaying debts of over £1,000, the new laws introduce a highly aggressive punishment: the government can apply to a court to temporarily disqualify the debtor from holding a driving licence.
-
Business as Usual Penalties: Despite public outcry, the government is currently writing to thousands of people with outstanding debts, heavily warning them to get in touch and pay up immediately, or face losing their ability to drive to work or take their children to school.
-
The “Essential Need” Exemption: The only safeguard preventing a driving ban under the DWP Joint Account Crackdown 2026 rules is if a claimant can prove in court that they have an absolute “essential need” for the licence—such as working as a delivery courier or holding intensive, daily caring responsibilities.
-
Suspended Bans: Any driving ban issued by the court is initially suspended, acting as a permanent threat over the claimant’s head as long as strict repayment terms are consistently met without a single missed month.
4. Legal Safeguards: How to Protect Your Finances Today
Even when national banking systems face widespread structural adjustments, specific legal safeguards and transitional rules must protect vulnerable groups trying to strictly comply with the DWP Joint Account Crackdown 2026 framework.
-
Separate Your Finances Immediately: Financial advisors strongly suggest that if you owe a historical benefit debt, you must legally uncouple your banking. Setting up a single, separate account ensures that your partner’s independent wages cannot be caught up in the DWP Joint Account Crackdown 2026 dragnet.
-
Contact Debt Management Before October: The government is aggressively telling claimants to “get in touch and pay up” now. Proactively calling the Debt Management department to arrange a highly affordable monthly payment plan is the only guaranteed way to stop them from issuing a Direct Deduction Order.
-
Demand a Breakdown and Appeal: If you receive a terrifying debt letter, do not instantly agree to pay it. Demand a full, written Mandatory Reconsideration to force the department to manually prove exactly how the debt was calculated. You also have the right to appeal to a first-tier tribunal before deductions begin.
-
Utilize Hardship Exemptions: The law dictates that deductions must not cause severe hardship in meeting essential living expenses (like food and accommodation). If the proposed deduction will leave you starving, you must formally apply for the order to be varied or cancelled based on extreme financial vulnerability.
5. Simple Checklist: Managing Your Bank Accounts
To ensure your financial setup remains entirely secure and unexpected government fraud nightmares are actively avoided, follow this highly practical checklist inspired by DWP Joint Account Crackdown 2026 defense strategies:
-
Audit Your Joint Accounts: Identify exactly whose money goes into every shared account. If your spouse’s salary is deposited there, the government will assume 50% of it is available to seize to pay your historical welfare debt.
-
Check for Old Letters: Look through your physical mail and digital journal for any old, ignored letters from the Debt Management team, as these are the final warnings before the October bank raids officially begin.
-
Submit Your Financial Evidence: If you share an account but the money belongs entirely to the other person, immediately gather pay slips, bank transfer records, and written statements to prove beneficial ownership to the authorities before the DWP Joint Account Crackdown 2026 sweep targets your household.
6. Frequently Asked Questions (FAQs)
Can the government actually take money without a court order?
Yes. Thanks to the new Public Authorities (Fraud, Error and Recovery) Act, officials now possess the explicit legal power to go directly to a person’s bank and forcibly claw back cash owed via a Direct Deduction Order, without ever needing a judge’s permission.
Will my partner’s money be safe?
If your partner’s money is sitting in a joint account that has your name on it, it is officially at risk. The welfare department has explicitly confirmed that joint accounts will be actively targeted, assuming a 50/50 split of the funds unless you can legally prove otherwise.
When do these new bank deduction rules start?
The department has confirmed that these extreme new recovery powers, including bank seizures and driving licence bans, will start being actively enforced beginning in October 2026.
Where can I check official UK welfare advice for these complex changes?
You can review authoritative government policies, legal defense strategies, and financial safety advice directly by visiting the official GOV.UK benefits portal or by speaking with independent debt charities like Citizens Advice.
Keeping up with ongoing DWP Joint Account Crackdown 2026 discussions is absolutely essential for protecting your financial freedom and organizing a stress-free financial setup for your family. DWP Joint Account Crackdown 2026 With banking and welfare frameworks facing continuous and highly aggressive evaluation, taking a few minutes today to review your bank accounts, separate your joint finances, and negotiate a payment plan can completely safeguard your monthly income from unexpected government seizures.
Make sure your financial arrangements are thoroughly audited before October arrives. Navigating these highly complex new banking and welfare realities successfully is the ultimate key to achieving long-term peace of mind. Understanding the extreme DWP Joint Account Crackdown 2026 implications is critical for anyone who has ever had a historical overpayment or shared a bank account with someone who has. For continuous updates, breaking financial news, and essential, life-saving claimant advice, make sure to bookmark and regularly visit Go Daily Buzz.
Join the conversation